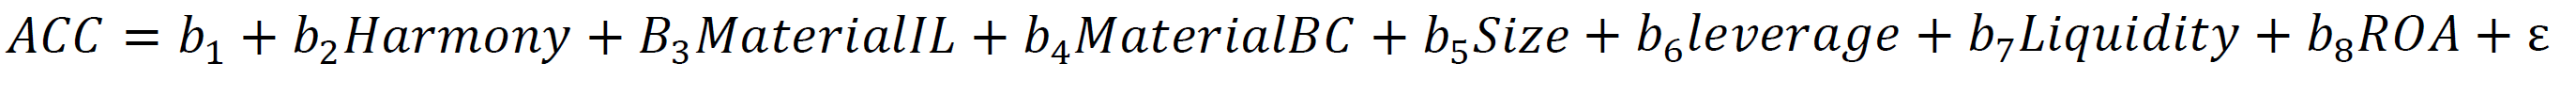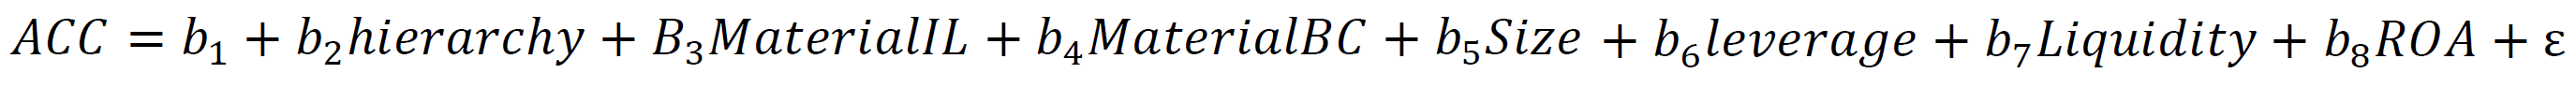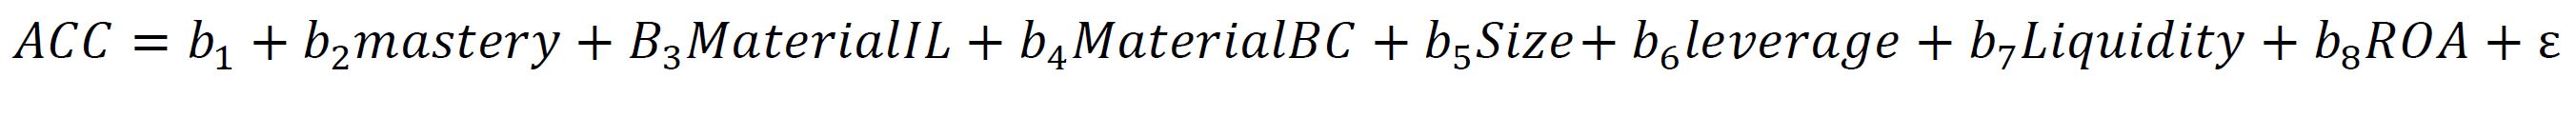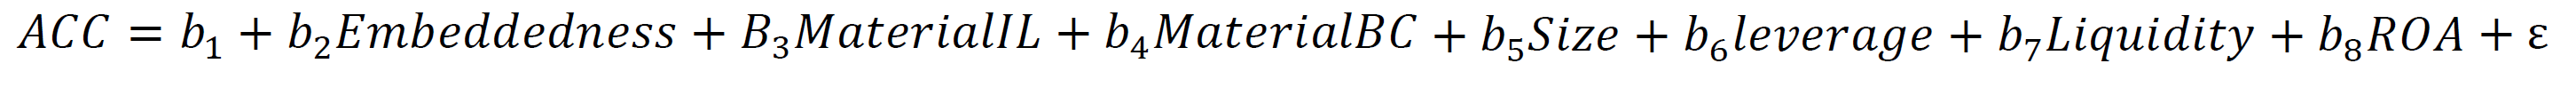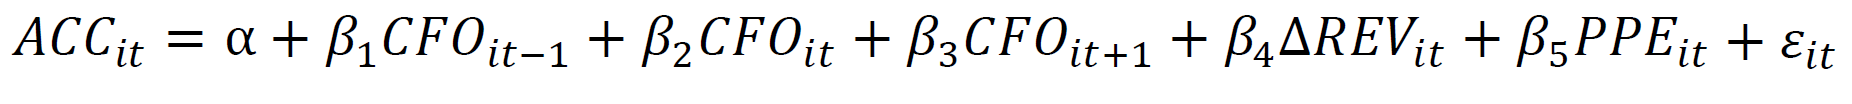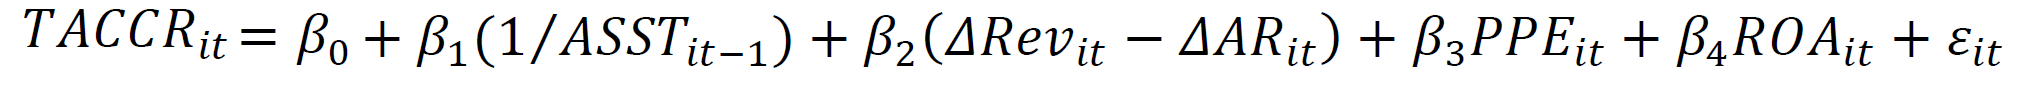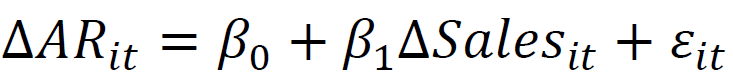The purpose of this study is to examine the impact of an ethical approach to accounting theory on enhancing financial reporting transparency. The geographical scope of the research includes companies listed on the stock exchanges of Iran, Turkey, Qatar, Bahrain, Iraq, Oman, Saudi Arabia, and the United Arab Emirates, and the time horizon covers the period from 2018 to 2024. This study is applied in nature. The sample consists of 2,029 firms listed on the aforementioned stock exchanges. The findings indicate that strengthening ethics-oriented components in accounting such as justice, integrity, accountability, and responsibility has a positive and statistically significant relationship with financial reporting transparency. In contrast, the dominance of self-interest-driven attitudes, authoritarianism, and mastery is associated with a negative and significant relationship with financial reporting transparency. Furthermore, hierarchical structures, by themselves, do not exhibit a statistically significant relationship with financial reporting transparency. Overall, professional ethics in accounting can influence various aspects of financial reporting. As social justice, peace, and economic security increase, financial reporting transparency is also enhanced. Accounting serves as a key mechanism for the optimal allocation of resources and the improvement of economic efficiency, consistent with signaling theory. Efficient resource allocation can contribute to social security and sustainable economic production. However, given that authoritarianism and mastery emphasize individual interests and considering that agency theory highlights conflicts of interest and opportunistic behavior when personal interests prevail over collective interests, the likelihood of opportunistic behavior and fraudulent reporting increases, ultimately leading to reduced financial reporting transparency.
Keywords
Ethical Approach
Accruals
Financial Reporting Transparency
Conflict of Interest
INTRODUCTION
A sizeable amount of previous research has analyzed the determinants of financial reporting transparency largely focusing on the peculiarities of specific firms. For example, Biddle, Hillary, and Verdi [1] posited that the profitability of a firm may influence financial reporting transparency, and Barth, Cram, and Nelson [2] demonstrate the positive reporting transparency effects of firm size. Cohen [3] posits that the operational cycle influences the amount of reporting transparency and financial leverage, according to Sun [4] is among the most important determinants of financial reporting transparency. However, Akman [5] suggests that prior to the establishing the disclosure requirements of the financial reporting standards, the ethical dimensions and value systems of the reporting entities were under analyzed in terms of their effects on the implementation and regulatory effectiveness of the requirements.
According to Douping and Alter, the values and norms governing members of the accounting system influence the choice and practice of accounting. In the same way, Gray [6] points out that the differences in accounting practices in the world cannot be explained only by micro and macroeconomic factors. Other underlying factors, such as ethical and cultural issues, are equally important. While the ethical and social values have been studied extensively in relation to the social system, much less attention has been given to the ethical dimension in explaining the building blocks of accounting and the effects this has on the clarity of financial reports.
According to the studies conducted by Hofstede [7] and Belkaoui [8], there are many different types of environments that affect the growth and change of the field of accounting, and among those environments, there are also social and economic environments that are of great importance. Due to the differing economic, social, and ethical environments, it is normal to see differences in the accounting systems and the clarity of financial reports offered by the systems in different countries. Given that accounting is a social and professional discipline, it is also a system that is heavily influenced by the environment of professional ethics. It can be said, therefore, that ethics can, through the influence that ethics has on the principal actors, shape the accounting system and its ultimate product, the financial statements along with the degree of clarity of those statements.
Research shows that ethical values in accounting may affect behaviors such as conservatism, secrecy, and professionalism, which, in turn, may affect the extent, reliability, and transparency of financial disclosures. Hope (2003) stated that financial reporting underestimates the ethical components, and accounting research should identify the relationship between the differing ethical beliefs and professional values and the accounting decisions made. These analyses have a significant impact on the researchers as well as the standard setters. This is also true for Gray, Kang, Lin and Tang [9] who cite the ethical and value-based factors as important in the differences in earnings management, especially with the presence or absence of tolerance towards opportunism and the extent of earnings management and the transparency of financial reporting. In the same vein, Fearnley and Gray [10] posit that the ethical values that are dominant in a country or organization may have a powerful impact on the choice of accounting methods, which, in turn, impacts the transparency of financial reporting and the volume of disclosures.
Having discussed this, it is clear that the research question of this study focuses on whether incorporating ethics within accounting theory can support the cause for improved transparency in financial reporting.
Theoretical Foundations and Literature Review
Financial Reporting Transparency: Financial reporting transparency considers different types of earnings. Dechow and Dichev [11] articulation states that transparency of the reports reflects the reporting firm's performance and the economic usefulness of the data to the firm's stakeholders. DeFond and Zhang [12] state that transparency in financial reporting shows the degree to which the financial reports of an organization purposively simplify the economic reality of that organization. Along these lines, the reports are useful. Although reports that contain the honest and complete mass of economic data may contain partial mass of data, they are better than reports that contain the complete mass of data. Reports that enhance mass data are central to transparency [13]. This concern is particularly true when reports are provided in an adequate and timely manner that may raise the endless concern of degree of transparency. Considering the recent trends in international accounting fraud, financial reports that are complete and honest have become a primary concern for the boards, shareholders, researchers, and accounting professionals. The financial reports that completely and honestly represent a firm's economic reality have particularly become a primary concern for the members of the boards, shareholders, researchers, and accounting professionals. This has especially become true in the wake of the recent trends in international accounting fraud.
Globally, three competing perspectives have been proposed regarding the relationship between firm characteristics and financial reporting transparency [14]. The first perspective suggests that structural characteristics of firms play a crucial role in constraining managerial manipulation of accounting figures, potentially more so than monitoring mechanisms or performance indicators. The second perspective emphasizes the effectiveness of governance mechanisms such as independent directors and institutional shareholders in curbing opportunistic managerial behavior in financial statement preparation. The third perspective posits that performance-related variables may be more effective than both structural and monitoring mechanisms in limiting unethical managerial activities that ultimately reduce financial reporting transparency.
Within this framework, the primary objective of financial reporting is to provide high-quality, transparent financial information about economic entities that is useful for economic decision-making [15]. Empirical studies assessing financial reporting transparency have employed various measurement approaches, many of which focus on earnings quality. Accrual-based models and value-relevance measures typically assume that earnings management reduces the decision usefulness of financial information and, consequently, diminishes financial reporting transparency ([16]. Dechow and Schrand [17] further note that most measures used in the earnings quality literature are grounded in the idea that certain accrual components reduce transparency, whereas the cash component of earnings generally enhances it.
From a broader theoretical perspective, Belkaoui [8] contends that every accounting system is a product of its surrounding environment and prevailing institutional conditions. In earlier work, Belkaoui [8] highlighted the role of accounting in management, social control, taxation, and public domains such as investment. Accounting is inherently a social activity that has evolved through human interaction and is profoundly shaped by individual perceptions, interpretations, and judgments concerning accounting concepts. Moreover, accounting systems are embedded within organizational contexts and derive their meaning and functionality from the institutional environments in which they operate.
When viewed as an information system, accounting may also be analyzed within the framework of behavioral accounting, an approach introduced by Hofstede [7]. In this context, Perera emphasizes that the human element in accounting is influenced by environmental factors, including cultural and societal values. Accordingly, it can be inferred that an ethical approach to accounting theory through its influence on the behavior of financial decision-makers and reporting agents can play a critical role in enhancing financial reporting transparency.
Culture
Hofstede [7] defines culture as the “programming of the collective mind” that distinguishes the members of one group from those of another [7]. Within the framework of the present study, this concept can be interpreted in terms of an ethical approach an approach that encompasses a shared set of values, beliefs, and norms that shape individuals’ behavior and their perceptions of the surrounding environment. The ethical approach is regarded as a fundamental concept in social and professional studies because it establishes a link between micro-level behavior (individual actions) and macro-level structures (organizational and societal systems), while influencing norms, values, and interaction patterns within and across social systems. In the accounting domain, an ethical approach may also influence decision-making frameworks, disclosure practices, and ultimately the level of financial reporting transparency.
Schwartz [18] introduces four value dimensions that can also be analyzed as dimensions of an ethical approach [18]. These dimensions include Embeddedness, Hierarchy, Mastery, and Harmony, each of which may shape professional judgments, disclosure practices, and ultimately financial reporting transparency.
Embedding focuses on the relationships both on the individual and the group level, as well as the extent to which individuals have an ethical liberty. In context-based autonomy, individuals are regarded as distinct and different, and as such, they are encouraged to manifest their distinct attributes, be it feelings, thoughts, or preferences. In such a context, however, the embeddedness structures, prioritizing the collective takes precedence over individual autonomy.
Hegemony emphasizes the acceptance of unequal role distribution, responsibilities, and the distribution of social goods. On the other hand, the egalitarian value orientation views individuals as a moral equal, and considers self-interest subsumed to the collective good.
Mastery refers to an orientation of control and purposeful management of the social and natural environments to realize one’s objectives. In such contexts, success, progress, and overcoming challenges are regarded as instrumental values.
In contrast, harmony emphasizes social balance, peace, social justice, and the balance of human relationships. Under this orientation, the end does not justify the means, such that objectives must not be accomplished through domination or exploitation of people and resources, but rather through positive and responsible interaction.
In previous research conducted internationally in the area of financial reporting and accounting methods, some research has focused on the role of social and ethical concerns in accounting systems. For instance, in his research on the accounting profession in Japan, and later in his work, Gray offered a model for the societal values/ accounting systems intersection using Hofstede’s value dimensions, which has received a considerable amount of attention [6]. In his analysis of accounting systems in various countries, Gray identified four accounting subcultures and illustrated how each of those subcultures influences the accounting system, and the transparency of financial reporting. Therefore, it can be deduced that the ethical disposition of a society or organization, through its impact on values and judgment, influences accounting practices, and, el a el, strengthens the transparency of financial reporting.
Financial Reporting Transparency and Culture
From the perspective of information induction theory, which is rooted in behavioral theories, accounting focuses on the behavior and actions of information senders and seeks to explain the factors influencing the decision to disclose or withhold financial information. In other words, this theoretical perspective emphasizes the role of human and value-based factors in the design and functioning of accounting systems. Within this framework, an ethical approach represents a fundamental variable that can influence the formulation, implementation, and interpretation of accounting practices.
Douping and Alter argue that the values and norms governing members of the accounting system influence accounting choices and procedures. This view implies that the ethical and value-based context of a society can significantly shape the level of financial reporting transparency. Differences in value systems across societies lead to diverse interpretations and judgments regarding accounting concepts, relationships, and requirements. In this regard, Belkaoui [8] emphasizes that the value-based and institutional environment affects the process of setting accounting standards.
Similarly, Schwartz [18], through a framework based on organized value structures, identifies dimensions such as autonomy versus conservatism, openness to change versus preservation of the status quo, egalitarianism versus self-enhancement, and harmony versus hierarchy. These dimensions, according to Schwartz, guide professional behavior and influence decision-making processes. A substantial body of research examining the interaction between accounting and the social environment further confirms that the development and evolution of accounting are shaped by environmental factors particularly ethical and cultural values [7].
Dins, Jeanjean, and Stolowy [19] explain the resistance to adopting International Financial Reporting Standards (IFRS) using values-based and institutional analysis. Conceptually, the value framework of a country can be crucial in defining the boundaries of corporate financial disclosure [14]. Adler [20] argues that value systems arise from larger cultural and moral systems, and Homer and Kahle [21] show, using a value–attitude hierarchy model, that inner and outer values impact attitudes and, consequently, individual actions. Such a standpoint leads to viewing reporting options in an economy as a professional choice characterized by the culture and ethical framework of that economy [22].
Considering these theories, the dominant ethical climate of the community and the organization has an impact on the professional discretion, the amount of disclosure, the management of earnings, the application of the accounting regulations, and, therefore, is critical in improving the transparency of financial reporting.
Therefore, the research hypotheses are as follows:
Main Hypothesis
An ethical approach to financial reporting transparency is significant.
Sub-Hypothesis 1: Right living (harmony) is significant to financial reporting transparency
Sub-Hypothesis 2: The level of hierarchy present within an organization significantly influences its transparency in financial reporting
Sub-Hypothesis 3: The degree of mastery an individual possesses significantly influences their transparency in financial reporting
Sub-Hypothesis 4: The degree of embeddedness an individual possesses significantly influences their transparency in financial reporting
Previous Research
Many studies in the past few years have focused on the significance of the role of an individual’s environmental values and ethical orientations in accounting and financial reporting. For instance, Baatwah et al. [23] studied the effect of tribal culture on the transparency of financial reporting in the Gulf Cooperation Council (GCC) countries and reported that tribal culture negatively impacts the transparency of financial reporting since it moderates the efficiencies of the internal control systems. Alina et al. also studied the impact of culture on the selection of accounting practices and other aspects of the discipline of accounting, and found that the selection of accounting practices is influenced by the organizational culture and the corporate governance structure. In the same way, Karataş et al., while studying the accounting accountability systems in the Islamic countries, reported that the corporate governance systems and cultural values shape the accounting systems. Additionally, while addressing the intersection of culture and accounting, Fang [24] argues that cultural and ethical values must be considered in the process of globalization. Fang suggests that cultural awareness will assist in anticipating the evolution of accounting in different countries and will aid in the comprehension of accounting regulations, standards, and the conduct of professionals in various countries. In Iran, Etemadi et al. [25] investigated the intersection of culture and management accounting. They concluded that the application of management techniques and tools that originated in the West may not be as effective in the value and organizational structure of Iran. In addition, Noravesh and Dianati-Deilmami [26] evaluated Gray’s model in Iran and found that the explanatory power of the model is unsatisfactorily weak. This could be due to the fact that accounting in Iran has not developed in accordance with the needs of the society, and that there is overwhelming reliance on foreign accounting systems from developed countries.
Method of Research
The researcher has adopted a combination of the library and the field for collecting data. The theoretical framework has been prepared based on reviewing extensively books, theory based articles, local and international, and the relevant websites and the empirical part includes the primary financial data of the companies. Specifically, the researcher has obtained the core financial statements of the companies listed on the targeted stock exchanges during the period 2018-2024.
The researcher obtained the required financial data for the non-Iranian markets from the official data source and the website of the respective stock exchanges. The data obtained was classified and organized on Microsoft Excel.
Target Population
The target population of this study consisted of companies listed on the stock exchanges of Iran, Turkey, Qatar, Bahrain, Iraq, Oman, Saudi Arabia and the United Arab Emirates as of the end of 2024. The reason for including the countries other than Iran was to strengthen the framework of the hypothesis and to provide a meaningful cross-country analysis of the ethical perspectives in different contexts. For example, the ethical and value-based context in Iraq is markedly different from that of Iran, Turkey and the Arab Gulf countries.
The sample was chosen from the population using a screening (elimination) approach based on the following criteria: companies should be listed before 2018 and continue to be actively traded until the end of 2024 without trading suspensions; they should not have altered their fiscal year during the research period; they should be outside the banking, investment, and financial intermediation companies due to their unique structural features; and they should have relevant financial information needed to test the hypotheses during the entire duration of the study.
In line with the above, a final sample of 1,729 companies was chosen, which include 212 from Iran, 427 from Turkey, 40 from Qatar, 40 from Bahrain, 700 from Iraq, 100 from Oman, 150 from Saudi Arabia and 60 from the United Arab Emirates.
Models of the Study
In an attempt to test the research hypotheses, the following regression models are used, aligned with the methodology adopted by Mazi et al. [27]:
Equation 1
Equation 2
Equation 3
Equation 4
After examining each of the cultural dimensions introduced by Schwartz [18] individually, the Sobel test is employed to assess the combined effect of these cultural components. Afterward, the cultural dimensions are combined into a composite index, and the overall impact of culture is assessed using the following regression equation.
Equation 5
Research Variables
Dependent Variable (Acc)
According to the theoretical framework of the study, the dependent variable is the transparency of financial reporting. For the evaluation of this construct, the following models are used:
Accruals
The following outlines the model developed by Francis, LaFond, Olsson, and Schipper:
Equation 6
ACC represents total accruals, calculated as net income minus operating cash flows. CFO denotes operating cash flows, REV is sales revenue, and PPE is property, plant and equipment.
In accordance with Francis et al. [28], and after estimating the model, negative residual standard deviation is treated as a measure of financial reporting transparency. In this sense, less variability of discretionary accrual (i.e., accrual quality) is considered a sign of more transparency regarding financial reporting.
As an alternative, the residuals of the performance adjusted modified Jones model are also used. This model, adjusted for firm performance, is specified as follows Equation 7
Equation 7
TACCR denotes total accruals, calculated as net income minus operating cash flowsASST is the company’s total assets from the previous year. ΔREV denotes the change in the company’s revenue from the previous year, scaled by the total assets of the previous year. ΔAR is the change in accounts receivable from the previous year, scaled by the total assets of the previous year. PPE is net property, plant, and equipment, scaled by the total assets of the previous year. ROA is return on assets, calculated as net income over total assets of the previous year.
Earnings Management
The following model of measuring earnings management by McNichols and Stubben [16] is used:
Equation 8
The first variable captures the change in accounts receivable. In contrast, the second variable captures the change in sales. Each variable is divided by total assets at the beginning of the year. The residual in this regression captures the change in accounts receivable due to sales changes. Therefore, the main proxy variable is calculated as the absolute value of this residual multiplied by negative one. Therefore, this measure as a proxy variable tends to demonstrate greater financial reporting quality (i.e., more transparency).
Earnings Persistence
To measure earnings persistence, the model proposed by Dechow and Dichev [17] is employed as follows:
Equation 9
ERNTt represents current-period earnings, and ERNTt- 1 denotes earnings from the previous period. This test is conducted as a time-series regression for all firms over the study period, and the coefficient β₁ is used as the measure of earnings persistence.
Independent Variable
Since this study's sample consists of firms from different countries in the Middle East, it is important to use an ethnically based measure that enables cross-country comparisons. Therefore, based on Mazi and Slack, the value framework proposed by Schwartz [18] is used. Schwartz describes four different value types. These value types are empirical, and cross-cultural in nature and can be defined as Embeddedness, Hierarchy, Mastery, and Harmony. Schwartz [18] used survey-based data analysis and created empirical indices for each of these value types. This study uses these indices as country-based proxies to measure the dominant ethical value.
Control Variables
Loss (MaterialIL): This variable is a dummy variable indicating whether a firm reports a loss for the period under review. It receives a value of 1 if the firm reports a loss and 0 if otherwise. Sloan [29] posited that deterioration of a firm’s performance increases the probability of concealment and misappropriation of assets. Thus, loss reporting is presumed to be inversely related to the transparency of financial reporting.
Business Combination (MaterialBC)
This is another dummy variable that takes 1 if the firm has subsidiaries or has undertaken a business combination and 0 if otherwise. Firms that have undergone business combinations typically have much more earnings manipulation, misappropriation of assets, and management of earnings [27]. Thus, this variable is presumed to be inversely related to the transparency of financial reporting.
Firm Size (Size)
Firm size is defined as the natural logarithm of the market value of total assets. As posited by Habib, Bhuiyan, and Islam, larger firms are likely to have more developed organizational structures, more clearly defined organizational objectives, more robust governance frameworks, and more effective governance processes. Less manipulation of information or misappropriation of assets is likely among larger firms and thus, firm size is presumed to be positively related to the transparency of financial reporting.
Leverage
Risk and the ability to take on additional debt through the financial structure of an organization is described as its leverage. The book value of equity is considered as leverage's denominator. Firms that are more debt-ridden may have more inducements to forge financial records to procure debt or to show an improved financial position. According to the study of Francis, LaFond, Olsson, and Schipper [28], it is stated that greater leverage is more likely to cause earnings to be manipulated and opportunistic actions, resulting in less transparency in financial reporting.
Liquidity
Liquidity is evaluated by measuring the total of a company's current assets against its current liabilities. The resulting figure is an indicator of the organization’s ability to pay off obligations that are due in the short term. Firms operating with high liquidity are expected to experience financial strain less frequently. This likely results in a reduced need to hide or falsify financial data. Therefore, liquidity serves as a driving force in reporting transparency in financial records.
Return on Assets (ROA)
The calculation of Return on Assets (ROA) identifies total assets as its denominator and net profit as its numerator. Financial performance that is subpar tends to induce an organization's leadership to engage in the concealment or manipulation of information. This serves to distract from, or hide, inefficiencies in the organization’s operations [30]. Therefore, the expectation is a positive relationship with the transparency of financial data to be directly correlated with ROA.
Descriptive Statistics
Descriptive statistics are presented in Table 1.
Table 1: Descriptive Statistics
Variable
Mean
Median
Max
Min
Std. Dev.
Financial Reporting Transparency – Model 1
-0.072
-0.051
-0.004
-0.238
0.065
Financial Reporting Transparency – Model 2
-0.084
-0.060
-0.004
-0.275
0.076
Financial Reporting Transparency – Model 3
-0.189
-0.099
-0.003
-0.804
0.220
Financial Reporting Transparency – Model 4
-0.304
0.310
4.240
-11.240
3.188
Harmony
3.960
3.980
4.230
3.200
0.174
Hierarchy
2.591
2.440
3.650
2.000
0.348
Mastery
3.902
3.940
4.300
3.340
0.136
Embeddedness
3.930
3.780
4.630
3.450
0.303
Loss (Dummy)
0.235
0.000
1.000
0.000
0.424
Business Combination (Dummy)
0.355
0.000
1.000
0.000
0.478
Size
13.600
13.710
17.160
9.734
2.043
Leverage
1.470
0.890
6.400
-1.090
1.760
ROA
0.052
0.041
0.270
-0.126
0.094
Liquidity
0.053
1.903
12.177
0.946
3.830
Descriptive statistics show that for the main variables of the study, measures of financial reporting transparency across different models show limited dispersion and largely homogeneous behavior across the firms sampled. However, one of the models shows significantly greater variation, which may indicate differing structures of capital markets, varying levels of institutional development, regulatory variation, and varying the enforcement of reporting standards in different countries. From an accounting viewpoint, the variation is warranted as financial reporting transparency is not a technical abstraction. Aside from the quality of measurement and recognition, managerial motives, governance structures, and the overarching ethical and value-based framework that exists influence the construct.
Relating to independent variables, the dimensions of the ethical approach (Harmony, Hierarchy, Mastery, Embeddedness) illustrate cross-country differences in value orientation, giving a solid foundation to formulate the research hypotheses. From the theory of accounting standpoint, these dimensions may have a bearing on professional judgment, a certain level of conservatism, disclosure, and opportunistic behavior. For instance, Harmony is often aligned with values of social justice, responsibility, and collective welfare, which is likely to improve transparency in reporting. On the other hand, Mastery and Embeddedness may create a facilitative environment for lower levels of disclosure and higher levels of non-disclosure.
From an accounting perspective, the control variables have valuable implications as well. The combination of losses and business combinations indicate that a portion of the firms’ functions within a framework of greater reporting risk. Increased losses could mean that management is more incentivized to commit earnings manipulation or present the firm in a more favorable light financially, reporting losses and business combinations could lead to decreased reporting transparency as a result of the complex measurements, flexible estimations, and greater managerial control that could lead to downward pressure reporting transparency. The size of the firm in the sample indicates that there were small firms and there were large firms, and larger firms usually have more robust governance mechanisms and greater regulatory control, which could increase the reporting transparency. The higher the firm’s level of leverage, the more likely management would be incentivized to conceal a higher level of risk and manipulate earnings, having a greater level of leverage would mean that the firm has a higher risk of covenants and other contractual obligations; therefore, the risk of the firm’s level of leverage would increase.
Finally, liquidity and return on assets show differences in financial condition and performance of firms across the sample. This variation is especially important for understanding reporting behavior, because firms facing poor performance or constraints in liquidity are more likely to manipulate earnings, delay reporting, or adopt accounting policies with flexibility. Overall, the descriptive statistics present the collection of data with enough financial, structural, and value diversity to support the analysis of the effect of ethics on transparency in financial reporting across countries.
Hypothesis Testing Results
Harmony has a significant effect on financial reporting transparency (Table 2).
Table 2: Results of the First Hypothesis Test (Harmony)
Variable
Financial Reporting Transparency 1
Financial Reporting Transparency 2
Financial Reporting Transparency 3
Financial Reporting Transparency 4
t-Statistic
Sig.
t-Statistic
Sig.
t-Statistic
Sig.
t-Statistic
Sig.
Harmony
3.870
0.000
0.230
0.000
3.857
0.000
1.803
0.007
Loss
1.760
0.078
1.314
0.188
1.277
0.201
1.343
0.179
Business Combination
-1.138
0.254
-1.029
0.303
-0.874
0.382
-1.032
0.301
Size
1.480
0.139
0.801
0.422
0.996
0.319
0.938
0.348
Leverage
-4.150
0.000
-3.773
0.000
-3.895
0.000
-3.835
0.000
ROA
-2.181
0.029
-2.538
0.011
-2.439
0.014
-2.548
0.010
Liquidity
-4.189
0.000
-3.819
0.000
-4.229
0.000
-3.902
0.000
Constant
-148.070
0.000
150.542
0.000
150.120
0.000
151.290
0.000
R-squared
0.690
-
0.601
-
0.602
-
0.603
-
Adjusted R-squared
0.540
-
0.532
-
0.541
-
0.505
-
F-Statistic
8.505
-
8.384
-
8.594
-
8.435
-
Prob (F-Statistic)
0.000
-
0.000
-
0.000
-
0.000
-
Durbin-Watson
2.345
-
2.145
-
2.324
-
2.238
-
Results from the table show the first sub-hypothesis examined the effect of Harmony on financial reporting transparency using four other models. Each model was evaluated for its t-statistics and significance levels.
Model 1 posits a t-statistic of 3.870 and a significance of 0.000 meaning there is a positive and statistically significant relationship at a high level of confidence. Model 2 offers a <0.230 t-statistic but reports 0.000 significance meaning in this specification, the relation is statistically significant. Model 3 t-statistic = 3.857, and significance = 0.000 which confirms a positive highly significant relationship for harmony and financial reporting transparency. Model 4 offers a t-statistic of 1.803 and significance of 0.007 which is significant at the 5 percent level supporting a positive relationship.
In all four models, the p-values are >0.05 and the t-statistics exceed conventional critical limits in most cases. This leads to the conclusion that the Harmony dimension positively and statistically significantly relates to transparency in financial reporting, Therefore, the first sub-hypothesis is accepted.
From an accounting viewpoint, this finding indicates that in settings that emphasize social justice, cooperation, and collective harmony, there is a greater tendency for fuller disclosure and less opportunistic behavior. Hence, these value orientations lead to improved transparency in financial reporting.
Sub-Hypothesis 2:
Hierarchy has a significant effect on financial reporting transparency. The results reported in Table 3 are analyzed for the second sub-hypothesis which states that Hierarchy positively impacts the financial reporting transparency by reviewing the t-statistics and the level of significance for each of the four model specifications.
Table 3: Results of the second Hypothesis Test (Hierarchy)
Variable
Financial Reporting Transparency 1
Financial Reporting Transparency 2
Financial Reporting Transparency 3
Financial Reporting Transparency 4
t-Statistic
Sig.
t-Statistic
Sig.
t-Statistic
Sig.
t-Statistic
Sig.
Hierarchy
1.749
0.804
1.743
0.814
-4.475
0.080
0.127
0.898
Loss
0.479
0.631
0.321
0.748
0.048
0.961
0.213
0.830
Business Combination
-0.387
0.698
-0.410
0.682
0.403
0.686
-0.261
0.793
Size
-8.255
0.000
-9.745
0.000
-9.394
0.000
-8.975
0.000
Leverage
6.992
0.000
6.390
0.000
7.252
0.000
6.647
0.000
ROA
10.129
0.000
11.248
0.000
9.893
0.000
10.173
0.000
Liquidity
-0.692
0.489
-1.156
0.247
-0.495
0.620
-1.104
0.269
Constant
67.521
0.000
73.586
0.000
65.495
0.000
64.321
0.000
R-squared
0.640
-
0.650
-
0.640
-
0.640
-
Adjusted R-squared
0.530
-
0.550
-
0.550
-
0.540
-
F-Statistic
6.145
-
6.518
-
6.249
-
6.343
-
Prob (F-Statistic)
0.000
-
0.000
-
0.000
-
0.000
-
Durbin-Watson
1.760
-
1.760
-
1.750
-
1.760
-
Model 1 yields a Hierarchy t-statistic of 1.749 and a significance of 0.804. This shows the effect of Hierarchy on financial reporting transparency is non - statistically significant. This is confirmed by the t-statistic of Model 2 being 1.743 and a significance of 0.814. Model 3 has a t-statistic of -4.475 and a significance of 0.080. This means that although the coefficient is negative, it is marginally significant at 10 % which is above the limit of 5% that is statistically significant in standard accounting research. Model 4 t-statistics is 0.127 and significance is 0.898 which shows that statistical significance is again lacking.
The Hierarchy variable impacts financial reporting transparency. Thus, the second sub-hypothesis is rejected. Given that in three of the models the p-values are significantly greater than 0.05, and only one model demonstrates weak and borderline significance at the 10 percent level, it can be concluded that Hierarchy lacks a statistically significant impact on financial reporting transparency.
From an accounting standpoint, this means that the existence of hierarchical systems in countries and organizations is not, in and of itself, a critical factor influencing the transparency of financial reporting. Their effects are likely only to be substantial in conjunction with other systemic elements, including the strength and enforcement of regulations, the quality of corporate governance, and the ethics of managers.
Sub-Hypothesis 3
Mastery has a significant effect on financial reporting transparency.
Sub-Hypothesis 4: The results in Table 4 pertaining to the third sub-hypothesis, which posits Mastery influences financial reporting transparency, were analyzed by evaluating the t-statistics and associated p-values across the four model specifications.
Table 4: Results of the second Hypothesis Test (Mastery)
Variable
Financial Reporting Transparency 1
Financial Reporting Transparency 2
Financial Reporting Transparency 3
Financial Reporting Transparency 4
t-Statistic
Sig.
t-Statistic
Sig.
t-Statistic
Sig.
t-Statistic
Sig.
Mastery
-4.276
0.000
-3.229
0.000
-0.466
0.043
-0.510
0.034
Loss
0.568
0.569
-0.757
0.448
0.020
0.983
-0.087
0.931
Business Combination
-2.280
0.022
-1.986
0.047
-3.098
0.002
-3.090
0.002
Size
4.985
0.000
2.897
0.038
2.096
0.036
2.073
0.038
Leverage
-7.684
0.000
-5.733
0.000
-4.501
0.000
-4.591
0.000
ROA
-9.571
0.000
-4.234
0.000
-4.126
0.000
-4.219
0.000
Liquidity
-1.404
0.160
-1.172
0.241
-1.779
0.075
1.916
0.055
Constant
662.670
0.000
365.091
0.000
426.662
0.000
416.840
0.000
R-squared
0.508
-
0.513
-
0.505
-
0.506
-
Adjusted R-squared
0.366
-
0.373
-
0.362
-
0.363
-
F-Statistic
3.570
-
3.650
-
3.520
-
3.530
-
Prob (F-Statistic)
0.000
-
0.000
-
0.000
-
0.000
-
Durbin-Watson
2.070
-
2.070
-
2.060
-
2.060
-
For Mastery in Model 1, the t-statistic is -4.276 and p = 0.000, which posits a negative and highly significant \reporting transparency effect that is a 1 percent and lower. Model 2 t-statistic = -3.229, p = 0.000, \reporting transparency also demonstrates a statistically significant negative effect. Model 3 demonstrates t-statistic = -0.466, p = 0.043 which posits that the effect is negatively directed and statistically significant at 5 percent. The t-statistic in Model 4 is -0.510, p = 0.034, which also demonstrates significance at 5 percent. Regarding all four models, all p-values are less than 0.05 and t-statistics are negative, suggesting that the Mastery dimension is less associated with financial reporting transparency. Hence, it is reasonable to assert that Mastery has a statistically significant and negative relationship with financial reporting transparency. Therefore, the third sub-hypothesis is statistically significant but the effect is not enhancing transparency, instead, it is reducing transparency.
This finding can be understood theoretically, given the discipline of accounting. Mastery traits involve dominating the control of one’s surroundings, achieving goals through a competitive approach, and exercising one’s will. Managers may have greater incentives to preserve their competitive, draw outside funding, or achieve goals which may make them more inclined to manage earnings. Managing earnings can involve less disclosure or painting the financial position more positively. Therefore, more Mastery is associated with less disclosure and more poor transparency in financial reporting.
Embeddedness has a positive connotation in relation to financial reporting transparency.
The table above testing the fourth sub-hypothesis shows the hypothesis that Embeddedness affects the transparency of financial reporting. I reviewed the t-statistics and the relevant significance levels from four different model specifications. In Model 1, the t-statistic for Embeddedness equals -7.955, with significance of 0.000, thus contributing a strongly negative and highly significant impact for financial reporting transparency. For Model 2, the t-statistic equals -4.804 with significance of 0.000, thus further confirming the relationship's negative direction and statistical significance. In Model 3, the t-statistic equals -3.450, with a significance of 0.000, as such the negative and significant effect of Embeddedness remains under this specification as well. In Model 4, with the t-statistic of -0.765, the significance level still holds at 0.003 thus remaining statistically significant at the 5 percent level. The effect still remains negative (Table 5).
Table 5: Results of the second Hypothesis Test (Embeddedness)
Variable
Financial Reporting Transparency 1
Financial Reporting Transparency 2
Financial Reporting Transparency 3
Financial Reporting Transparency 4
t-Statistic
Sig.
t-Statistic
Sig.
t-Statistic
Sig.
t-Statistic
Sig.
Embeddedness
-7.955
0.000
-4.804
0.000
-3.450
0.000
-0.765
0.003
Loss
1.687
0.091
3.162
0.000
2.164
0.030
2.821
0.005
Business Combination
2.075
0.038
1.562
0.118
0.874
0.382
1.463
0.143
Size
-3.623
0.000
-2.718
0.006
-2.242
0.025
-2.008
0.044
Leverage
-1.931
0.054
-4.475
0.013
-2.474
0.013
-2.612
0.009
ROA
-2.233
0.025
-1.577
0.114
-1.685
0.092
-1.299
0.194
Liquidity
0.956
0.338
0.837
0.402
0.892
0.372
0.657
0.511
Constant
77.020
0.000
78.330
0.000
77.184
0.000
78.890
0.000
R-squared
0.559
-
0.554
-
0.554
-
0.550
-
Adjusted R-squared
0.432
-
0.425
-
0.425
-
0.420
-
F-Statistic
4.395
-
4.295
-
4.286
-
4.227
-
Prob (F-Statistic)
0.000
-
0.000
-
0.000
-
0.000
-
Durbin-Watson
2.370
-
2.432
-
2.370
-
2.320
-
All four models have p-values under 0.05 with t-statistics consistently negative. This implies that more Embeddedness means less financial reporting transparency. So, Embeddedness does have a statistically significant, negative relationship with financial reporting transparency. Hence, the fourth sub-hypothesis is supported regarding statistical significance, but the evidence indicates a decrease in transparency, rather than an increase.
An accounting viewpoint on this result makes sense. In embedded or authority heavy environments, decision making is fairly centralized, meaning accountability and transparency are deprioritized. These environments promote the hiding of information, less disclosure, more managerial self-interest, and, ultimately, less transparency in financial reporting.
Main Hypothesis:
An ethical approach has a significant effect on financial reporting transparency.
Based on the regression results reported in Table 6, the main hypothesis stating that the ethical approach has a significant effect on financial reporting transparency—was tested.
Table 6: Overall Results of Hypothesis Testing
Variable
Coefficient
Std. Error
t-Statistic
Sig.
Ethical Approach
0.030
0.010
3.000
0.000
Loss
0.036
0.020
1.765
0.078
Business Combination
0.008
0.024
0.316
0.752
Size
-0.013
0.006
-2.260
0.023
Leverage
0.022
0.005
4.004
0.000
ROA
0.501
0.129
3.880
0.000
Liquidity
-0.002
0.004
-0.502
0.615
Constant
14.441
0.080
178.411
0.000
R-squared
0.303
-
-
-
Adjusted R-squared
0.101
-
-
-
F-statistic
2.505
-
-
-
Prob(F-statistic)
0.000
-
-
-
Durbin-Watson
1.532
-
-
-
The coefficient of the ethical approach variable is 0.030, with a t-statistic of 3.000 and a significance level of 0.000. Since the p-value is below 0.05, it can be concluded that the effect of the ethical approach on financial reporting transparency is statistically significant. Moreover, the positive sign of the coefficient indicates a direct relationship, meaning that higher levels of ethical orientation are associated with higher levels of financial reporting transparency.
Regarding the explanatory power of the model, the reported R-squared value of 0.303 indicates that approximately 30 percent of the variation in financial reporting transparency is explained by the variables included in the model. The F-statistic of 2.505 with a significance level of 0.000 confirms that the overall regression model is statistically significant. In addition, the Durbin–Watson statistic of 1.432 suggests that there is no serious autocorrelation problem in the model.
From an accounting perspective, this finding is theoretically interpretable. Focusing on ethics can also reinforce the importance of honesty, responsibility, and stakeholder-centered decision-making, and can strengthen managerial incentives on disclosure and disclosure, and less on opportunistic behavior. In an ethically oriented organizational and institutional context, it will be better to predict the transparency of financial reporting. That said, the empirical evidence reinforces the primary hypothesis of the study.
Conclusions and Suggestions
The ethical approach may be the most important principle in the field of social and professional studies because it is the one that connects the micro and the macro, and links the individual, the organization, and the society. This will be the aim of the current study, to investigate the impact of the ethical approach to accounting theory on the transparency of financial reporting using data from companies listed on the stock exchanges of Iran, Turkey, Qatar, Bahrain, Iraq, Oman, Saudi Arabia, and the United Arab Emirates.
Several studies show that the different stages of growth of accounting are determined by a number of different factors, and in accounting, the ethical values and norms of a given society or organization play a crucial role.
For instance, Ding et al. [19] associate resistance to the implementation of International Financial Reporting Standards with value-based and institutional contexts. Accounting practices are also directly linked to the environment in which firms operate, and conceptually it can be argued that the ethical climate of a country plays a determining role in the level of disclosure and transparency of corporate financial information. Therefore, as ethical and value-based environments vary, reporting practices are also expected to differ.
From the perspective of Douping and Alter the values and norms governing members of an accounting system influence accounting practices, and the findings of the present study support this view. In other words, in Middle Eastern or West Asian countries, differences in ethical orientations and value systems contribute to variations in the level of financial reporting transparency. Similarly, Baatwah et al. [23] demonstrate that in Gulf countries, social and value-based contexts can significantly influence financial reporting transparency.
The existence of diverse ethical approaches within accounting environments leads to different interpretations and professional judgments regarding accounting concepts and relationships. Therefore, standard setters should take ethical contexts and value-based subcultures into account when developing accounting standards and financial regulations. Furthermore, accounting systems evolve within organizational settings and derive their meaning and function from the ethical and institutional environment in which they operate; thus, the ethical approach constitutes an inseparable component of financial reporting systems.
With respect to the hypothesis testing results, the findings related to the Harmony dimension suggest that higher levels of social justice, peace, and security are associated with improved financial reporting transparency. This is because accounting serves as a key mechanism for optimal resource allocation and enhanced economic efficiency (signaling theory), and efficient resource allocation can contribute to social security and sustainable economic activity. Regarding Mastery and Embeddedness—theory dimensions that relate to control, power, and self-interest—findings are congruent with agency theory. When self-interest predominates over the interest of the group, opportunistic behavior, earnings manipulation, and fraudulent reporting occur, which diminishes the transparency of financial reporting. These results also corroborate the findings of the present study and those of Baatwah et al. [23].
Lastly, it would be beneficial to integrate an ethical perspective as a major consideration in establishing accounting laws and financial regulations. Every society has a distinct set of mechanisms to reinforce disclosure and transparency that are aligned with its ethical and value-oriented framework. Particularly, in settings characterized by a higher degree of Mastery and Embeddedness, the laws and regulations are designed to counterbalance the dominance of self-interest over public interest. Additionally, it would be beneficial if future studies would address the ethical aspects related to auditing, the quality of audits, and the oversight of finances.
REFERENCE
Biddle, G., Hillary, G. and Verdi, R. “How does financial reporting quality improve investment efficiency?” J Account Econ vol. 48, 2009, pp. 112–138.
Barth, M.E., Cram, D. and Nelson, K. “Accruals and the prediction of future cash flows.” Account Rev vol. 76, 2001, pp. 25–58.
Cohen, A. “Quality of financial reporting choice determinants and consequences.” Northwestern University; 2004.
Sun, J. “Financial reporting quality, capital allocation efficiency, financing structure: an international study.” Shanghai University; 2005.
Akman, N.H. “The effect of IFRS adoption on financial disclosure: does culture still play a role?” Am Int J Contemp Res vol. 1, no. 1, 2011, pp. 6–17.
Gray, S.J. “Towards a theory of cultural influence on the development of accounting systems internationally.” Abacus vol. 24, no. 1, 1988, pp. 1–15.
Hofstede, G. “Culture’s consequences: international differences in work-related values.” Beverly Hills CA: Sage; 1980.
Belkaoui, A. and Maksy, M. “Welfare of the common man and accounting disclosure adequacy: an empirical investigation.” Int J Account. 1985, pp. 94.
Gray, S.J. et al. “Earnings management in Europe post IFRS: do cultural influences persist?” Manag Int Rev vol. 55, no. 6, 2015, pp. 827–856.
Fearnley, N. and Gray, S. “National institutional factors and IFRS implementation in Europe.” Int J Account Inf Manag vol. 23, no. 3, 2015, pp. 271–288.
Dechow, P. and Dichev, I. “The quality of accruals and earnings: the role of accrual estimation errors.” Account Rev vol. 77, 2002, pp. 35–59.
DeFond, M. and Zhang, J. “A review of archival auditing research.” J Account Econ. 2014.
Brown, J., Falaschetti, D. and Orlando, M. “Auditor independence and earnings quality: evidence for market discipline vs. Sarbanes-Oxley proscriptions.” Am Law Econ Rev vol. 12, no. 1, 2010, pp. 39–68.
Jaggi, B.L. “The impact of the cultural environment on financial disclosure.” Int J Account vol. 10, no. 1, 1975, pp. 75–84.
International Auditing and Assurance Standards Board. “International standard on auditing 240: the auditors’ responsibility relating to fraud in an audit of financial statements.” IFAC.
McNichols, M. and Stubben, S. “Does earnings management affect firms’ investment decisions.” Account Rev vol. 86, 2008, pp. 1571–1603.
Dechow, P. et al. “Understanding earnings quality: a review of the proxies, their determinants and their consequences.” Haas School of Business, University of California, Berkeley; 2009.
Schwartz, S. “Beyond individualism/collectivism: new cultural dimensions of values.” In: Kim, U. et al. editors. Individualism and collectivism: theory, method and applications. Beverly Hills CA: Sage; 1994, pp. 85–119.
Ding, Y. et al. “Why do national GAAP differ from IAS? The role of culture.” Int J Account vol. 40, no. 4, 2005, pp. 325–350.
Adler, N. “International dimensions of organizational behavior.” Ohio: International Thomson Publishing; 1997.
Homer, P.M. and Kahle, L.R. “A structural equation test of the value-attitude-behavior hierarchy.” J Pers Soc Psychol vol. 54, no. 4, 1988, pp. 638–646.
Tony, K. et al. “The impact of culture on accounting choices: can cultural conservatism explain accounting conservatism?” Asia Pacific Interdisciplinary Research in Accounting Conference; 2004.
Baatwah, S.R. et al. “Culture and financial reporting quality in GCC countries: what do we know about tribal culture?” Int J Emerg Mark. 2021.
Fang. “On accounting and culture.” Can Soc Sci vol. 3, no. 5, 2007, pp. 121–124.
Etemadi, H. et al. “Culture, management accounting and managerial performance: focus Iran.” Adv Account vol. 25, 2009, pp. 216–225.
Noroush, A. and Dianti Deilami, Z. “Investigating the impact of cultural values on accounting in Iran.” Account Audit Rev vol. 10, no. 3, 2003.
Mazzi, F. et al. “The effect of corruption and culture on mandatory disclosure compliance levels: goodwill reporting in Europe.” J Int Account Audit Tax 2018.
Francis, J. et al. “Costs of equity and earnings attributes.” Account Rev vol. 79, 2004, pp. 967–1010.
Sloan, R. “Do stock prices fully reflect information in accruals and cash flows about future earnings?” Account Rev vol. 71, 1996, pp. 289–315.
Lu, Y. et al. “Investment-related pressure and audit risk.” Auditing vol. 36, no. 3, 2017, pp. 137–157.
Recommended Articles
Research Article
Country of Origin and Foreign Branding on Perceived Quality of Local Products in Indonesia: The Moderating Role of Consumer Ethnocentrism
Download PDF
Research Article
The Effect of Self-Efficacy and Working Environment on Work Achievement with Organizational Commitment as Mediation
Sri Wahyuni,
...
Veithzal Rivai Zainal
Download PDF
Research Article
The Effect of Information Technology Utilization, Apparatus Competence, and Organizational Commitment on Managerial Performance of Financial Management in the SKPK Simeulue District Government
Cut Nining Rapinus,
...
Indayani
Download PDF
Research Article
The Effect of Employer Attractiveness and Compensation on Job Persuit Intention to Fmcg Companies in Indonesia: Coporate Reputation as an Intervening Variable
Download PDF
PO Box 101, Nakuru
Kenya.
Email: office@iarconsortium.org
Editorial Office:
J.L Bhavan, Near Radison Blu Hotel,
Jalukbari, Guwahati-India
Hassoon, A. R. (2026). The Impact of an Ethical Approach to Accounting Theory on Enhancing Financial Reporting Transparency. Scientific Research Journal of Economics and Business Management, 6(1), 1-10.
MLA
Hassoon, Aqeel R.. "The Impact of an Ethical Approach to Accounting Theory on Enhancing Financial Reporting Transparency." Scientific Research Journal of Economics and Business Management 6.1 (2026): 1-10.
Chicago
Hassoon, Aqeel R.. "The Impact of an Ethical Approach to Accounting Theory on Enhancing Financial Reporting Transparency." Scientific Research Journal of Economics and Business Management 6, no. 1 (2026): 1-10.
Harvard
Hassoon, A. R. (2026) 'The Impact of an Ethical Approach to Accounting Theory on Enhancing Financial Reporting Transparency' Scientific Research Journal of Economics and Business Management 6(1), pp. 1-10.
Vancouver
Hassoon AR. The Impact of an Ethical Approach to Accounting Theory on Enhancing Financial Reporting Transparency. Scientific Research Journal of Economics and Business Management. 2026 Jan;6(1):1-10.


 Download PDF
 Download XML